
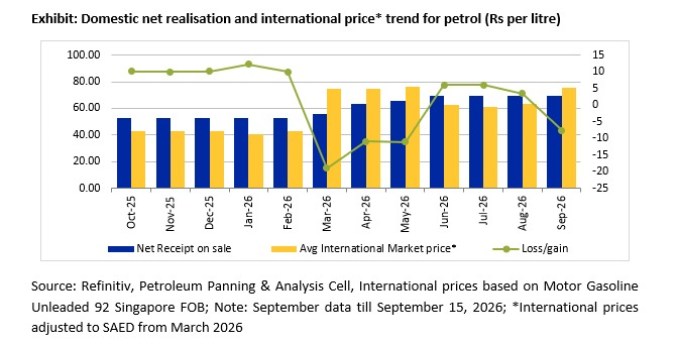
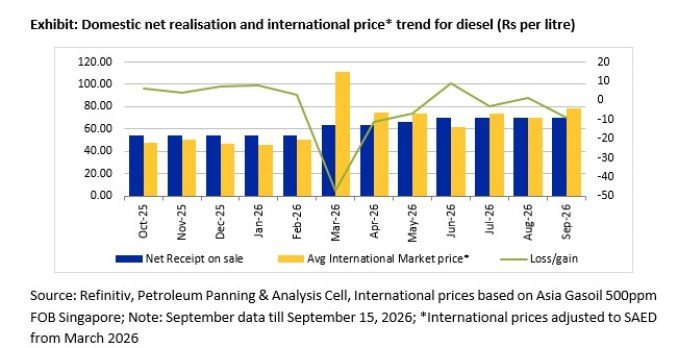
• With domestic retail prices remaining unchanged, OMCs’ marketing margins were estimated at negative Rs 8 per litre on petrol and negative Rs 9 per litre on diesel currently
• Domestic LPG under-recoveries stood at around Rs 300 per cylinder in September 2026
Rating agency ICRA estimated the marketing margins of the oil marketing companies (OMCs) at negative Rs 8 per litre on petrol and negative Rs 9 per litre on diesel, and the domestic liquefied petroleum gas (LPG) under-recoveries at around Rs 300 per cylinder in September 2026. This follows from the recent spike in crude oil prices amidst domestic retail prices of the downstream fuels remaining unchanged.
Commenting on the sector outlook, Mr Prashant Vasisht, Senior Vice-President and Co-Group Head, Corporate Sector Ratings, ICRA said, “The escalation of the West Asian conflict and disruptions to key oil supply routes have led to a spike in crude prices in recent weeks, resulting in sizeable marketing losses and LPG under-recoveries for OMCs. With domestic retail prices remaining unchanged so far, the marketing margins of OMCs were estimated at negative Rs 8 per litre on petrol and negative Rs 9 per litre on diesel, while domestic LPG under-recoveries stood at around Rs 300 per cylinder in September 2026. At these levels, the daily loss to the OMCs is estimated at Rs 5.30 billion.”
Crude oil prices have increased sharply in recent weeks amid escalating geopolitical tensions and supply disruptions in West Asia. The surge was driven by renewed US-Iran conflict, the shutdown of Saudi Arabia’s East-West pipeline and heightened Houthi activities in the Red Sea. The Indian crude basket rose to $117.4 per barrel (bbl) as on September 21, 2026 from the 2025-26 average of around $66 per bbl.
“Elevated crude prices and unchanged domestic fuel prices would put pressure on profitability and cash flows of OMCs. The same would also elevate their short-term borrowings for increased working capital requirements. The impact on OMCs’ earnings in 2026-27 will depend on crude prices, product cracks, retail price revisions and government support for LPG under-recoveries.” Vasisht added.
The cumulative negative LPG buffer increased sharply to Rs 619.40 billion as on June 30, 2026, as the rise in international LPG prices following the West Asian supply disruptions was not fully passed on to consumers. The estimated loss per domestic cylinder stood at ~Rs 500 in Q1 2026-27 and remained at around Rs 300 in September 2026. LPG under-recoveries are likely to rise further if elevated international prices persist without a commensurate increase in domestic selling prices or additional Government compensation.
Singapore gross refining margins have remained above $10 per bbl since the start of the West Asia crisis, supported by refinery and product supply disruptions, inventory drawdowns and outages across West Asian refining capacity. Additional supply shortages arising from damage to Russian refineries further tightened product markets, supporting elevated refining margins.
As product prices increased, export levies in the form of the special additional excise duty (SAED) on diesel and aviation turbine fuel were introduced from March 27, 2026, and subsequently extended to petrol. For domestic supplies, SAED is adjusted in the refinery transfer price, reducing the effective product cost for marketing divisions of OMCs. The SAED on these fuels has remained high at Rs 20 per litre on diesel and Rs. 15 per litre on ATF since September 16, 2026, reflecting the strong cracks for these fuels.